As a premier global middle market investment bank, FOCUS partners with owners to deliver results through expert M&A, capital raising, and strategic advisory.
CEO Interview: From Trusted Partner to Strategic Sale
September 1, 2026
A transaction built on decades of relationships, operational excellence, and the right advisory at the right time.
CFE International was built over three decades through entrepreneurial instinct, calculated risk, and a deep commitment to its customers. Con Lynch and his business partner Pat Dennehy grew the company from a niche die refurbishment operation into a market leader in the UK and Ireland, earning a reputation that extended well beyond their borders. Along the way, a series of bold decisions shaped the business CFE is today.
The first of those decisions came just six months into the business, when CFE invested in a patented Danish die-refurbishment system unlike anything else available in the market. It was an expensive, unproven machine, but Con saw its potential immediately. This bold decision paid off because the patent created a meaningful barrier to entry in the UK and Ireland, giving CFE a competitive moat that its rivals simply could not replicate.
"Purchasing that machine so early on was a huge milestone. It put a barrier to entry from other competitors, but it was also a very expensive machine. We didn't expect anybody else to take us on there."
Con Lynch
Co-Founder, CFE International
Expansion into the UK followed quickly. One roadblock they hit came when customers were hesitant to send their assets across borders to a new, unfamiliar supplier. The solution was simple: put down roots in the UK. That decision proved critical to earning trust and scaling the business on both sides of the Irish Sea.
Not every move was a success, but leadership learned lessons from each decision. One of the biggest lessons learned was transparency. Transparency, he found, rarely costs as much as people fear.
As the company expanded and a financial crisis hit, the business faced its most consequential strategic decision yet: consolidate or be consumed by overhead. CFE chose consolidation and pivoted to concentrating production in the UK. It was a significant step for an Irish company, but the right one.
The most transformative milestone was winning the agency agreement for CPM which they saw as the global leader in die press equipment. This agreement elevated CFE’s market positioning, signaled credibility to customers, and planted the seed of the relationship that would eventually define the company’s next chapter.
Knowing it was the right time
For many founders, the hardest question is not whether to sell — it is when.
Leadership recognised that the business had reached a natural inflection point. CFE held strong market share in the UK and Ireland, and the logical next step was European expansion. What CFE needed required capital, risk, and bandwidth that they would have had to shoulder largely alone.
Lynch said, “It’s hard to win alone. If we wanted to move the business to the next phase, we would have to borrow again — and you’re alone in a different country. It made sense to find a strong partner.”
Why CPM Was the Right Partner
CFE had a long-standing relationship with CPM. This relationship mattered enormously when it came to evaluating fit.
The connection between the two companies traces back to 2002, when CPM first approached CFE about manufacturing dies. CFE became a CPM agent in 2010. CFE’s consistent sales performance and reliable execution gradually shifted the dynamic, and what had begun as a commercial arrangement matured into something far more substantial.
For Con and Pat, the criteria for a partner went well beyond valuation. They needed someone with an established European presence and reach in the markets they wanted to enter. They needed assurance that CFE’s UK and Irish customers, relationships built and nurtured over thirty years, would be protected and valued, not deprioritised in favour of newer markets. Most importantly, they needed cultural alignment from a buyer who understood that the business was its people and its relationships, not simply its equipment and revenue.
CPM checked every box. As the world leader in its sector, it brought global scale. Its existing presence across Europe and the Americas provided the geographic foundation CFE needed to grow. And the pre-existing relationship meant that trust, while not unconditional, was already established.
“Relationships are so important. If we had sold to a company with no existing relationship, we would have found it very difficult,” commented Lynch.
The Buyer’s Perspective
CPM was attracted to CFE both strategically and personally. CPM had already reached out to Con and Pat to express interest in acquiring the business before a formal process began.
"Con and Pat are both very special people in terms of the relationships they've built with customers. We've had a great focus to get closer to our customers and provide broader full lifecycle support — and that's something CFE does exceptionally well."
Dave Webster
Former CEO, CPM Holdings
CPM applies a disciplined acquisition framework, evaluating targets against a clear set of criteria. CFE’s unique expertise in die refurbishment represented a genuine capability gap for CPM. Its deep customer relationships in the were also an asset that could not simply be replicated or purchased elsewhere.
Equally important was the team. Con and Pat had built an organisation around people who understood and embodied the CFE way of working. For CPM, acquiring that team was a key part of the rationale, not an afterthought.
Navigating Complexity
All transactions have complications and this transaction was no different. As the transaction progressed, CPM became the subject of an acquisition by Rosebank Industries.
For Con, the news landed with an uncomfortable jolt. A process that had already demanded considerable patience and focus now risked losing its momentum entirely as CPM’s leadership turned their attention to their own deal. The concern was legitimate: distractions at the buyer level can delay, derail, or quietly kill a transaction.
This is where the value of FOCUS became most visible. Rather than allowing anxiety to build on the CFE side, Brian and the FOCUS team maintained a calm, methodical approach drawing on their prior experience. Brian’s previous experience gave Con the reassurance he needed. FOCUS made sure to provide ongoing reassurances, directly from CPM’s CEO, that the acquisition of CFE remained a priority. Weekly updates kept Con and Pat informed without overwhelming them with detail. The emphasis was always keeping management focused on the one thing within their direct control: running the business.
Dave Webster credits FOCUS with managing the communication carefully on both sides, ensuring that the sellers remained well advised and composed through a period that could easily have become destabilising. The transaction with Rosebank closed first; the acquisition of CFE followed within weeks.
“FOCUS did a really masterful job making sure that Con and Pat were calm through the process. They were incredibly well advised, and I think that kept everyone on track,” Webster added.
FOCUS understood that the deal’s success depended on maintaining the trust and goodwill that Con and Pat had spent years building with CPM’s leadership.
What Comes Next
The acquisition closed at an opportune moment for both parties. Rosebank Industries, as CPM’s new owners, had arrived with a clear strategic priority: accelerate the growth of CPM’s aftermarket business, and do it quickly.
“They acquired CFE to learn from it, not to change it,” said Lynch. “They want to understand this model and apply it. CPM has service centers right across Europe, the Americas and the world — and they want to upgrade those centers to look like what CFE has built.”
For CPM, the aftermarket business, the recurring, relationship-driven revenue, sustains the business across economic cycles. CFE’s approach to customer service, built on deep personal relationships, technical expertise, and consistent delivery, is precisely the capability CPM needed.
For Con and Pat, there is something deeply gratifying in that outcome. They built CFE over thirty years not simply to sell it, but because they believed in what they were building. Hearing CPM’s leadership talk about replicating the CFE model globally is one of the highest possible validation of the choices they made along the way.
For founders considering a similar path, Con offers four pieces of advice.
Don’t try to do it yourself: Perhaps the most emphatic piece of advice. Running a business and managing a sale simultaneously is almost impossible. A sale process directly impacts the business’s profitability and EBITDA. Taking your eye off operations during a transaction can cost far more than the advisory fees saved by going it alone.
Build a consistently profitable business: Buyers value businesses on EBITDA multiples. Sustained profitability drives valuation. If the business is not yet profitable, make that the first priority and maintain it for at least two to three years before considering a transaction.
Own the customer relationship directly: From the earliest days of the CPM agency, Con resisted arrangements that would have allowed CPM to deal with CFE’s customers directly, with CFE receiving only a commission. That insistence on owning the relationship proved to be one of CFE’s most powerful assets.
Develop a tangible, defensible competitive advantage: CFE’s USP was not invented by a marketing team. It was earned through technology investment, operational expertise, and years of consistency which gave them a competitive advantage.
“We concentrated on the bread and butter — making sure the business continued to run,” said Lynch. “FOCUS was a safe pair of hands. Don’t try to do it yourself.”
The CFE story is a reminder that the best transactions are rarely just about the numbers. In this situation, CPM was a known buyer with an existing relationship and the process was still complex and uncertain at times. The right advisor doesn’t just add value when the buyer is unknown; it is often critical when you think you don’t need it. If you are a founder considering your next chapter, FOCUS would welcome the conversation.
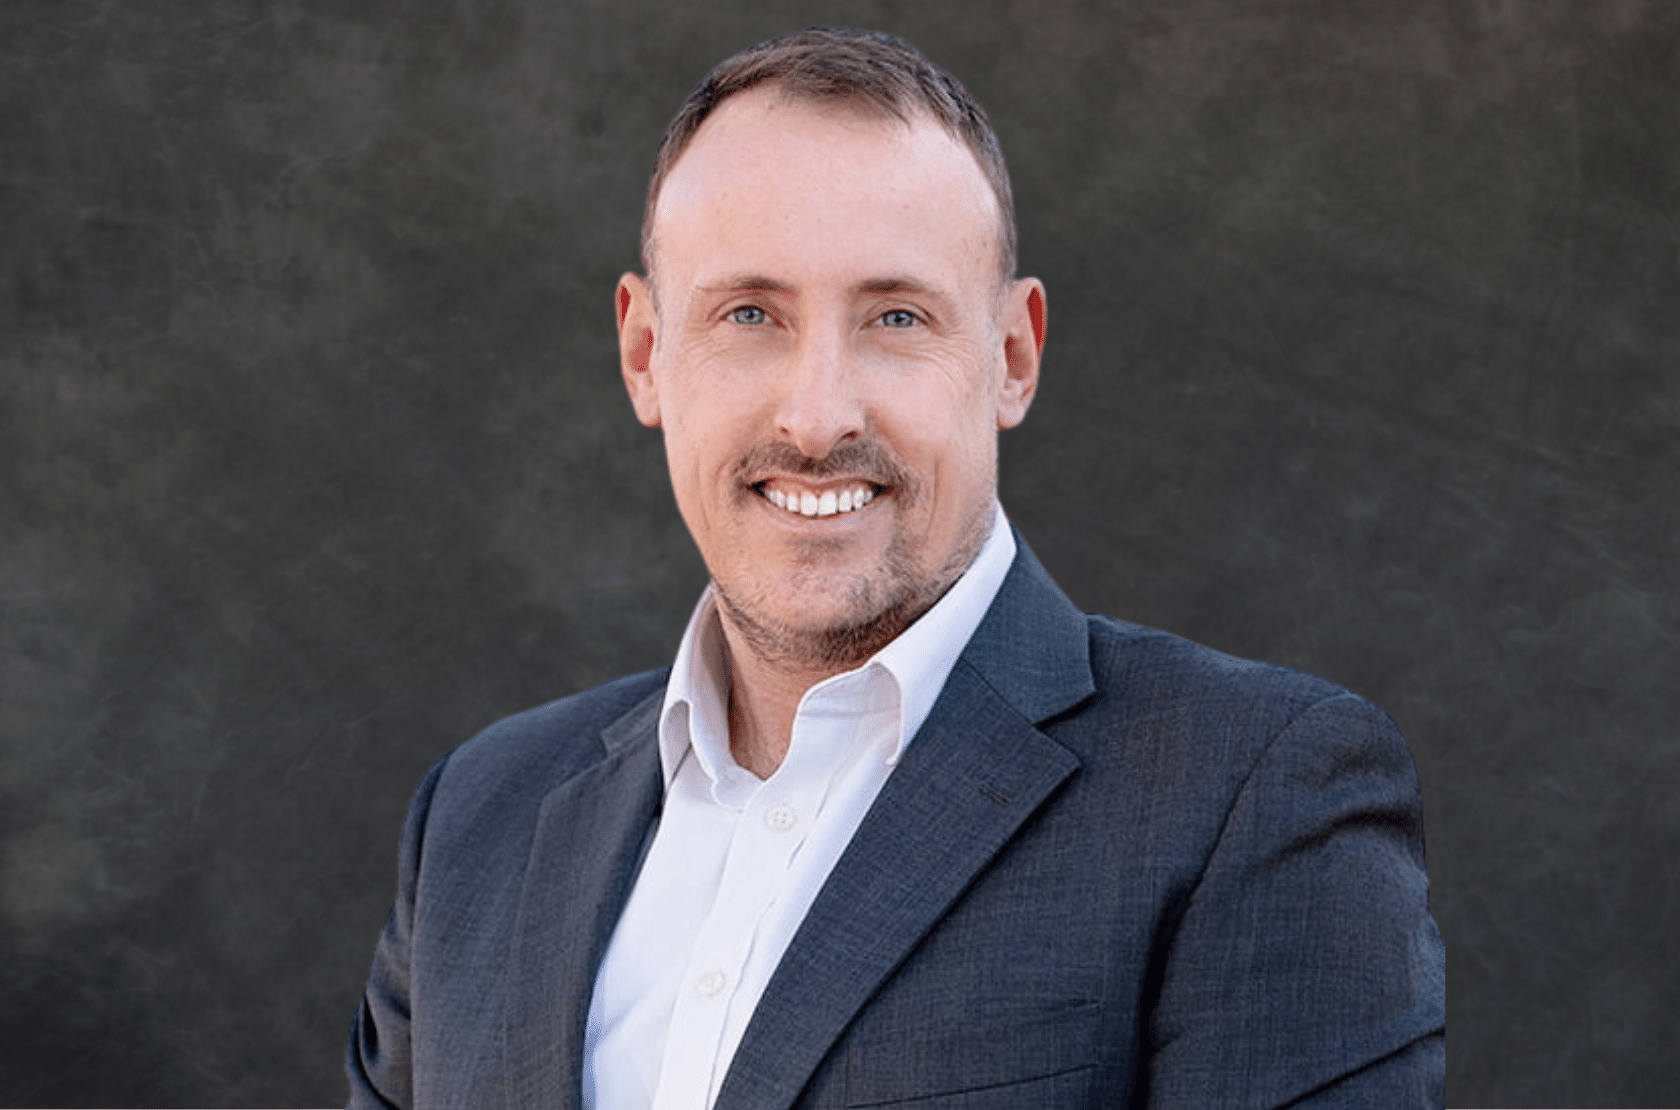
Written by
Brian Barrett
Managing Director
Brian Barrett, a FOCUS Managing Director, is a leading and experienced corporate finance advisor, who provides a broad range of services from debt advisory, valuations, due diligence, strategic planning, along with buy-side and sell-side lead advisory services to clients.
Whether you’re exploring a sale, raising capital, or simply want an outside perspective on where your business stands, our bankers are ready to listen. Reach out to start a confidential conversation with the FOCUS team.